Option Greeks Explained: Delta, Gamma, Theta and Vega with Simple Examples
Quick answer: Option Greeks are numbers that estimate how an option's premium will change. Delta shows the change for a 1-point move in the underlying. Gamma shows how fast Delta itself changes. Theta is the premium an option loses each day as time passes. Vega is the change for a 1-point move in implied volatility. Rho covers interest rates and barely matters for short-dated Indian options. They come from a pricing model, they change all day, and they make the most sense when you read them together.
Many beginners buy an option, see the market move their way, and still lose money. The Greeks explain why. SEBI's study of individual F&O traders, published in September 2024, found that about nine in ten lost money over three years. Not understanding how premiums behave is one of the reasons we see again and again in our classes.
This guide explains each Greek in plain words, then puts them together in one worked example. The numbers are round and hypothetical, quoted per unit of the option. To get a rupee figure for a trade, multiply by the lot size, and check the current lot size on the NSE website because it is revised from time to time.
About this guide: it's written by the Mentor Aditya Jain Academy team in Jaipur to explain what the option Greeks mean, with a worked example. It isn't advice to buy or sell anything, and we don't give tips or buy and sell calls.
What are option Greeks?
An option's premium depends on a few things: where the underlying is compared with the strike, how much time is left, how volatile the market expects things to be, and interest rates. Each Greek isolates one of those and tells you how sensitive the premium is to it.
Greek | What it measures | Plain way to think of it |
Delta (Δ) | Premium change for a 1-point move in the underlying | The speedometer |
Gamma (Γ) | Change in Delta for a 1-point move | How hard the accelerator is pressed |
Theta (Θ) | Premium lost per day from time passing | Daily rent on the option |
Vega (ν) | Premium change for a 1-point change in implied volatility | The fear and excitement meter |
Rho (ρ) | Premium change for a 1% change in interest rates | Mostly background noise for weekly options |
Your broker's option chain usually shows these next to each strike. They are estimates, not guarantees, and they shift every time price, time or volatility changes.
Delta: how much the premium moves with the market
Call options have a Delta between 0 and 1. Put options have a Delta between 0 and −1. An at-the-money option sits near 0.5 (or −0.5 for a put). Deep in-the-money options move almost one-for-one with the underlying, so their Delta is close to 1. Far out-of-the-money options barely react, so their Delta is close to 0.
Example. An index is at 24,000. The 24,000 call trades at ₹150 with a Delta of 0.50. If the index rises 60 points, the premium should rise by about 0.50 × 60 = ₹30, to roughly ₹180. A 24,000 put with a Delta of −0.45 would fall by about ₹27 on the same move.
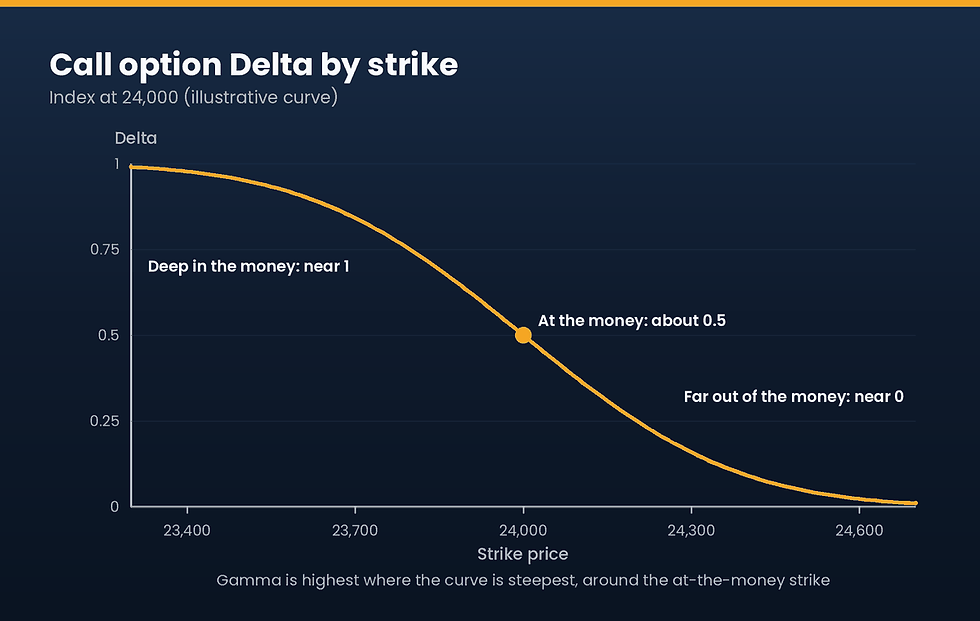
Traders also use Delta as a rough guide to the chance of an option expiring in the money. A 0.20 Delta call is, very loosely, a one-in-five shot. It is a rule of thumb, not a precise probability, but it is a useful reality check before buying cheap far out-of-the-money options.
Gamma: why Delta changes so fast near expiry
Gamma tells you how much Delta will change when the underlying moves 1 point. It is highest for at-the-money options and rises sharply in the last few days before expiry.
Example. Our 24,000 call has a Delta of 0.50 and a Gamma of 0.002. If the index rises 100 points, Delta climbs to about 0.50 + (0.002 × 100) = 0.70. The option now gains ₹0.70 for each further point instead of ₹0.50.
This is why a cheap option on expiry day can multiply in value within minutes, and why it can go to zero just as fast. For buyers, high Gamma works in their favour when the move comes. For sellers, high Gamma near expiry is the biggest danger, because losses accelerate as the market moves against them.
Theta: the daily cost of holding an option
Theta is the amount of premium an option loses each day if nothing else changes. Brokers show it as a negative number for option buyers.
Example. The 24,000 call at ₹150 has a Theta of −9. If the index closes flat tomorrow and volatility stays the same, the premium will be around ₹141.
A useful way to read Theta is as a break-even move. Divide Theta by Delta: 9 ÷ 0.50 = 18. The index needs to move about 18 points in your favour every day just for the option buyer to stand still.

Time decay isn't linear. An at-the-money option loses value slowly when expiry is weeks away and very quickly in the final few sessions. That is why holding weekly options for "one more day" costs more than most beginners expect.
Vega: the volatility effect
Vega shows how much the premium changes when implied volatility (IV) changes by 1 point. IV is the market's estimate of how much the underlying will move. For the Nifty, India VIX gives a quick read on it.
IV usually rises before known events such as results, the Union Budget or policy announcements, and falls once the news is out. That fall is often called an IV crush.
Example. Before a results announcement, a call trades at ₹150 with IV at 18 and Vega of 7. After the results, IV drops to 13, a fall of 5 points. That alone takes about 7 × 5 = ₹35 off the premium, even if the stock moves slightly in your favour.
Options with more time to expiry carry more Vega, so they react more to volatility changes than weekly options.
Rho, briefly
Rho measures sensitivity to interest rates. For weekly and monthly index options in India, rate changes are small compared with the life of the option, so Rho rarely matters. You can safely put it last on your list.
Putting the Greeks together: one worked example
You buy the 24,000 call at ₹150. Its Greeks are Delta 0.50, Gamma 0.002, Theta −9 and Vega 7. Over the next two days, the index rises 80 points and IV drops 2 points.
Effect | Working | Change in premium |
Delta | 0.50 × 80 | +₹40.0 |
Gamma bonus | ½ × 0.002 × 80 × 80 | +₹6.4 |
Theta (2 days) | −9 × 2 | −₹18.0 |
Vega | 7 × (−2) | −₹14.0 |
Net | about +₹14.4 |
So the premium ends near ₹164. An 80-point move in your favour earned about ₹14 per unit, not the ₹40 that Delta alone suggested. This is an approximation, because Theta grows each day and the Greeks keep changing, but it shows how time and volatility can quietly take back most of a correct directional call.
How to use option Greeks before you trade
Start with your view. Write down how far you expect the underlying to move and by when. Without a time frame, the Greeks can't help you.
Pick an expiry that gives the move enough time. If your idea needs a week to play out, a weekly option close to expiry will lose too much to Theta.
Choose the strike using Delta. Directional buyers often stay between 0.40 and 0.60 Delta. A 0.10 Delta option needs a big, fast move to pay off.
Check the Theta break-even. Divide Theta by Delta. If the daily move you need looks unrealistic, change the strike or the expiry.
Look at IV before events. If IV is far above its usual level ahead of an announcement, expect a drop afterwards and factor in the Vega hit.
Size by premium at risk. Decide the maximum you'll lose on the trade, and set both a price exit and a time exit.
If you sell options, respect Gamma. Near expiry, losses on short options can grow fast. Define your maximum loss with a hedge rather than hoping the market stays still.
Option Greeks for buyers vs sellers
Every option trade has two sides, and the Greeks that help one side hurt the other.
Greek | Option buyer | Option seller |
Delta | Gains when the market moves their way | Gains when it doesn't move much or moves their way |
Gamma | Helps: gains speed up on a big move | Hurts: losses speed up on a big move |
Theta | Hurts: pays time decay every day | Helps: collects time decay every day |
Vega | Helps when IV rises | Helps when IV falls |
Neither side is "safer" by default. Buyers have limited loss but fight Theta. Sellers collect Theta but carry open-ended risk unless they hedge.
Option Greeks in crypto trading
The same Greeks apply to options on Bitcoin and Ether. The difference is in scale. Crypto options trade around the clock, and their implied volatility is usually far higher than that of equity indices, so Theta and Vega are much larger relative to the premium. Some platforms quote the Greeks in coin terms rather than in dollars, which changes how you read the numbers.
Crypto derivatives aren't regulated by SEBI, so check who runs the platform and how your funds are held before trading. If crypto options are your main interest, the Cryptocurrency Market Course with AI covers perpetuals, options, Greeks and hedging for that market.
Mistakes beginners make with option Greeks
Buying far out-of-the-money weekly options because they look cheap is the most common one. Their low Delta means they barely move unless the market makes a large move quickly, and Theta takes a big percentage of the premium every day.
Holding a bought option through an event without checking IV is a close second. Many traders get the direction right on results day and still lose because the volatility crush outweighs the move.
Others treat the Greeks as fixed numbers. Delta at 10 a.m. isn't Delta at 2 p.m. after a 150-point move, so recheck before adding to or adjusting a position.
Some sell options for "regular income" without respecting Gamma near expiry. A few quiet weeks can be wiped out by one sharp move.
And many size positions on premium alone. A ₹20 option and a ₹200 option can carry very different risk once you look at their Delta and the lot size.
If you are new to derivatives, our guide on how to start futures and options trading in India covers the basics to learn before Greeks.
Option Greeks in Hindi: a quick recap
Delta batata hai ki index 1 point chale to premium kitna chalega. Gamma batata hai ki Delta kitni tezi se badlega, aur expiry ke paas yeh sabse zyada hota hai. Theta roz ka time decay hai: option buyer ka nuksaan, seller ka fayda. Vega batata hai ki IV 1 point badle to premium kitna badlega. Results ya kisi bade event ke baad IV girta hai, to premium bhi gir jaata hai, chahe direction sahi ho.
Learning options with us
At Mentor Aditya Jain Academy, Greeks are taught as part of the F&O pillar of the Global Stock Market Course with AI: Delta, Gamma, Theta and Vega in practice, IV, and hedge structures, with an F&O scenario sheet you fill in before each trade. The course includes five years of access and updates, WhatsApp chat and toll-free line support from the Personal Guidance Desk.
The F&O pillar comes after the basics, so the Greeks make sense by the time you reach them. We don't teach the common option setups that are free everywhere online, since everyone using the same trades is a big reason most of them lose. The strategies follow how institutions trade options, and each one is backtested, with the backtest shown to you.
Personal Guidance Desk on WhatsApp
A real person on our Personal Guidance Desk answers chats on the official WhatsApp (063-5033-9545), with no pressure to join. We respect your privacy. We never make spam or follow-up calls. If you prefer, call us on toll-free 1800-202-8034 or chat on WhatsApp 063-5033-9545. If something about option Greeks isn't clear, you're deciding between the free course and a paid course, or you have any other trading question, send it to the Personal Guidance Desk on WhatsApp.
Frequently asked questions
What are option Greeks in simple words?
They are numbers that estimate how an option's premium will react to a change in the underlying price (Delta), the speed of that change (Gamma), the passage of time (Theta), a change in implied volatility (Vega) and interest rates (Rho).
Which option Greek is most important for beginners?
Start with Delta and Theta. Delta tells you how much the option gains or loses as the market moves, and Theta tells you what holding the option costs each day. Add Vega whenever there is an event such as results or the Budget coming up.
What is a good Delta for buying options?
There is no single right number, but many directional buyers stay between about 0.40 and 0.60 Delta. Options with very low Delta are cheap for a reason: they need a large, quick move to make money.
Why does my option premium fall even when the market moves in my favour?
Usually because Theta and Vega are working against you. If the move is small or slow, daily time decay can outweigh the Delta gain, and a drop in implied volatility after an event can take more off the premium.
What does negative Theta mean?
It means the option loses that much value per day from time passing, if price and volatility stay the same. A Theta of −9 means the premium falls by about ₹9 a day for a buyer, and that amount grows as expiry gets closer.
Do option Greeks work for crypto options?
Yes, the same Greeks apply to options on Bitcoin, Ether and other crypto assets. Implied volatility in crypto is usually much higher, so Theta and Vega are larger relative to the premium.
Where can I see option Greeks in India?
Most broker option chains show Delta, Gamma, Theta, Vega and IV for each strike. The NSE option chain shows implied volatility, and many options analytics tools calculate the full set of Greeks.